
Investment spreadsheets hide the real problem. Monthly bills, especially car expenses, eat up fixed checks long before market swings do.
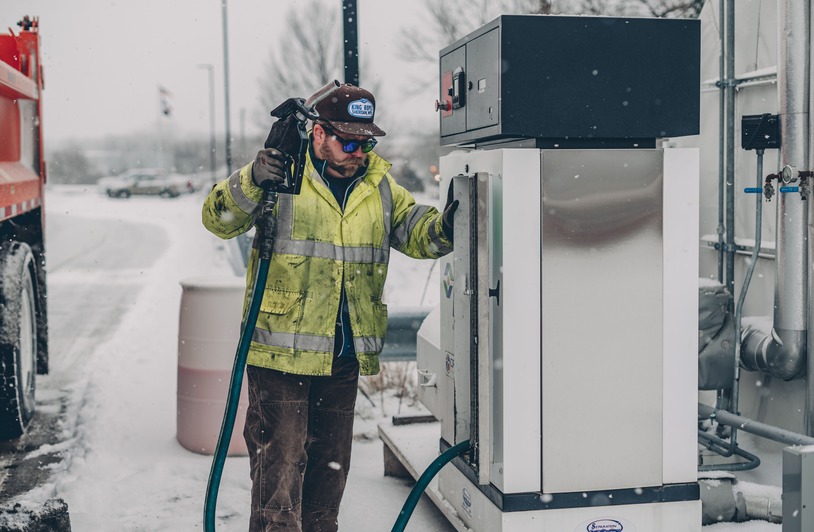
Daily errands and family trips don’t stop after career life ends. Gas is non-negotiable. If paying full price at the pump can be avoided with minimal effort, continuing to swipe a standard debit card is just bad math.
The Long-Term Weight of Routine Transit Overhead
Standard financial advice fixates on asset allocation and total net worth. Predictable daily operational expenses are what actively pressure a fixed monthly income.
Fuel is a perfect example of this. You do not just pay for gas once, and the need for it does not stop when your career ends. Many retirees actually drive more because they finally have the freedom to travel.
Even minor shifts in pump prices can disrupt your monthly budget. Finding ways to offset these costs frees up real cash for your long-term plans.
Transportation as a Long-Term Budget Category
People rarely discuss transportation when they talk about retirement plans. They focus heavily on housing and healthcare instead. But your ability to get around directly shapes your quality of life.
You need gas to see grandkids, go to doctor appointments, and stay independent. While you can cut back on some expenses, driving costs remain remarkably steady. Saving even a small percentage on fuel adds up to real money over the years . You do not have to drive less. You just have to manage the cost better.
Squeezing Value Out of Regular Fill-Ups
The gas bill is completely non-negotiable. Swiping a plain debit card at the station simply lets money bleed out for no reason. Running every tank through a credit card with gas perks keeps that regular expense lower over the course of an entire year.
Small rebates look minor on single purchases, but they change spending discipline over time. Earning automatic value back turns passive bills into tracked expenses. Routine station stops shift from an unmonitored leak into a controlled budget category. The overall cost does not disappear, but managing fixed overhead systematically protects limited monthly income.
A Practical Example of Fuel Reward Optimization
Look at the BP Rewards Visa as a practical example. This card gives you cash back on gas and other everyday purchases.
You can view the program details here: BP Rewards Visa Program
For retirees, the big draw is simplicity, not complex rules. Since you already buy gas, using a rewards system requires zero lifestyle changes. The program runs quietly in the background of your normal day.
The real power is in the consistency. Small returns stack up over time, especially on an expense you cannot avoid.
Why Basic Payment Setups Work Best
A sustainable budget cannot rely on spreadsheet obsession. Tracking every fractional cent drains energy, but ignoring built-in savings burns money. Practical tools should cut costs without creating extra chores. If a payment program forces people to jump through hoops and memorize rotating perks, it is useless. The right system applies rebates to regular driving expenses instantly, keeping monthly overhead low without the headache.
The Compound Effect of Small Overhead Cuts
Fixed-income timelines span decades. Shaving a few percentage points off fuel costs looks negligible on a single tank, but the total builds substantial capital over ten or twenty years. That recovered margin stays in reserve for actual priorities like medical expenses or leisure travel. Keeping everyday overhead tight removes the friction from managing a fixed monthly draw.
Conclusion
Gas remains a permanent, non-negotiable expense. Letting that money flow out without shaving off a percentage is pure waste. A simple pump perk handles the problem automatically, keeping fixed-income spending predictable month after month.
CLICK HERE TO DONATE IN SUPPORT OF DCREPORT’S NONPROFIT MISSION
